PropAMMs lower Solana trade costs, and public pool returns crash
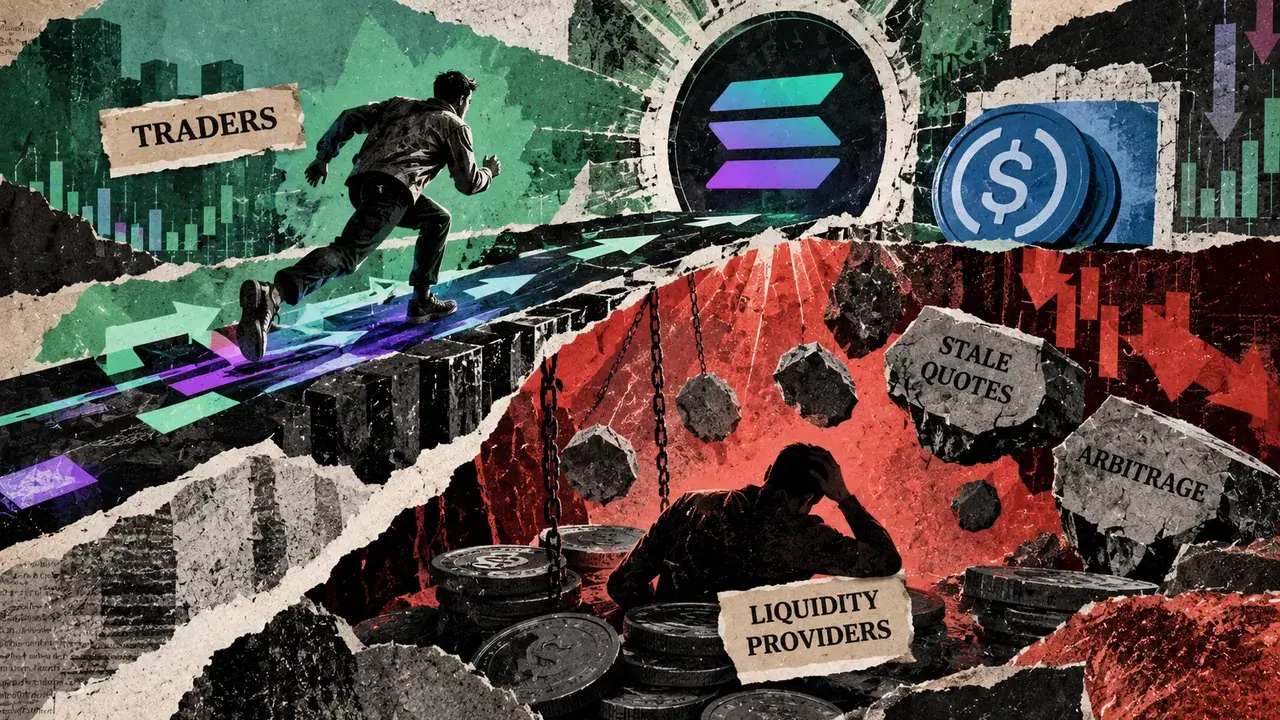
A study of SOL/USDC trades found professional automated market makers (propAMMs) had much lower reference-relative execution costs in quiet markets than public AMMs: 0.26 versus 2.59 basis points. Their two-second maker markouts were also better, but these short-horizon measures do not establish LP profitability, which depends on fees, inventory exposure, hedging and other costs. The findings distinguish cheaper swaps from returns to passive liquidity providers. On Base, Tessera executions averaged worse than reconstructed prior-block quotes; researchers label the fee pattern “spoofing” but provide no evidence of intent. The analysis argues routers should compare executable outputs for the same trade, caller, pool state and charges, while emphasizing that routing improvements do not resolve LP investment returns.